If you’re buying or selling a home in Warner Robins, you’ve probably heard about flood insurance. But what you may not know is how closely it connects to your closing date. Right now, the National Flood Insurance Program (NFIP) is facing a critical deadline. Unless Congress renews it by September 30, no new or renewed NFIP flood insurance policies will be issued. That’s a big deal for anyone with property near Bay Gall Creek, Mossy Creek, or low-lying parts of Bonaire and Kathleen. And this is where a flood elevation certificate can make the difference between closing on time and seeing your deal stall.
What an NFIP Lapse Really Means
When NFIP lapses, banks and mortgage lenders cannot rely on its policies to cover properties in Special Flood Hazard Areas. That doesn’t mean flood risks disappear—it means the main insurance option buyers and sellers count on suddenly goes off the table. For families already under contract, that gap could stop closing in its tracks.
Even if Congress acts quickly, history shows that even short lapses cause thousands of real estate transactions across the country to be delayed. A single week of uncertainty can ripple through every step of a sale. For buyers, that means extra days of waiting and possible rate lock issues. For sellers, it means sitting on a property longer than expected. For Realtors and lenders, it means headaches, lost time, and frustrated clients.
Why the Flood Elevation Certificate Matters
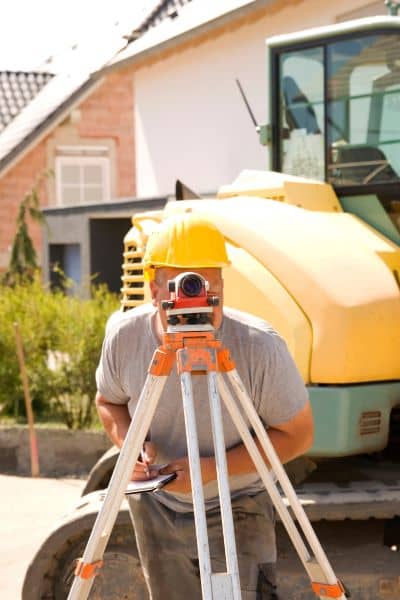
So how can a flood elevation certificate step in during all this? It’s simple: it proves where a structure stands compared to FEMA’s base flood elevation. Think of it as the official record card of how high your home sits relative to potential floodwaters.
With this document in hand, you can shop private flood insurance quickly—something many buyers and lenders turn to when NFIP is paused. Private insurers want reliable data before writing policies, and the elevation certificate is what gives them that confidence. Without it, you’re left guessing, and guessing doesn’t get a loan cleared for closing.
In Houston County, plenty of homes are mapped into flood zones even though they sit on higher ground. A current elevation certificate can show that your property isn’t as risky as the map suggests. That can unlock cheaper private policies and keep your transaction moving while Washington sorts itself out.
Local Impact: Closings at Risk
Let’s make it real. Imagine a couple buying their first home near a creek. Their lender requires flood insurance before releasing funds. Normally, that’s no problem—they’d get an NFIP policy, send proof to the lender, and close on time. But during a lapse, NFIP won’t issue a new policy.
Without insurance, the lender cannot move forward. The closing date gets pushed back. The sellers start worrying about their own next move. Everyone is stuck.
Now picture the same couple with a flood elevation certificate in hand. Their Realtor connects them with a private insurer who reviews the document, sees the actual elevation, and writes a policy in days. Instead of waiting on Congress, the deal moves ahead. That’s the power of being prepared.
What Realtors and Lenders Should Do Right Now
If you’re a Realtor, start checking FEMA flood maps for your listings. If a property touches a shaded zone, talk with your clients about ordering an elevation certificate early. That way, if NFIP goes into a pause, you already have the data needed to explore private options.
For lenders, it’s about keeping deals alive. An elevation certificate can be the difference between telling a buyer, “We need to wait,” and saying, “We have another path.” By encouraging early action, you reduce the risk of stalled files sitting on your desk.
Buyers should also take note. Asking about a flood elevation certificate during due diligence shows you’re serious and helps protect your timeline. It’s one of those small steps that saves big stress later.
How Past Lapses Have Played Out
This isn’t the first time NFIP has come down to the wire. Previous lapses, even when brief, caused thousands of real estate closings to be delayed. Properties in flood zones simply could not move forward without insurance.
It’s not about whether NFIP will eventually be renewed—it almost always is. It’s about how to protect yourself in the meantime. If you’re under contract in late September, you don’t want your deal to depend on political timing. Having an elevation certificate ready is one of the few things you can control.
Turning Preparation into Peace of Mind
Buying or selling a home is stressful enough. Add in a flood insurance deadline and it can feel overwhelming. But preparation changes the story. Flood elevation certificates transform uncertainty into action. Instead of waiting on a federal program, you can show private insurers the hard numbers, prove your property’s elevation, and keep your closing on track.
For homeowners, that means peace of mind. For Realtors, it means protecting your reputation as someone who solves problems before they happen. For lenders, it means keeping your pipeline moving.
Final Thoughts
Flood insurance rules may change at the federal level, but you don’t have to let them change your closing date. If you’re buying or selling the smartest move you can make right now is to secure a flood elevation certificate before the NFIP deadline hits.
At the end of the day, a simple survey document can be the bridge between an anxious delay and a smooth closing. Don’t leave it to chance. Act early, stay ahead, and let your deal move forward—no matter what happens in Washington.